Trading education · Economic releases
FOMC Explained: Rate Decisions, Statements and Dot Plots
Understand FOMC meetings, basis points, policy statements, press conferences, projections and minutes, with an example of expectations versus the decision.
Explore the guide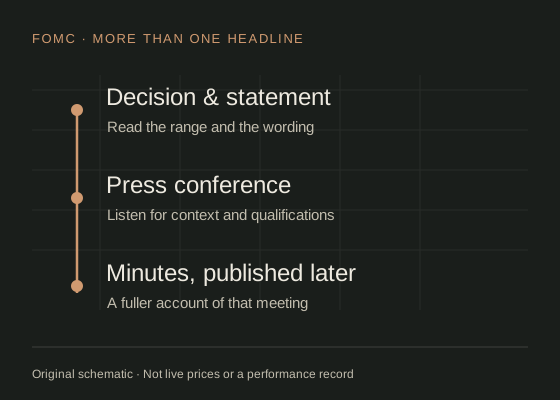
The short answer
The Federal Open Market Committee makes US monetary-policy decisions. A meeting produces more information than a rate headline: the statement, projections when published, and press conference can change expectations about the future path. Minutes arrive later and describe the meeting discussion.
What the FOMC does.
The Federal Open Market Committee is the Federal Reserve body responsible for monetary-policy decisions, including the target range for the federal funds rate. Its decisions influence financial conditions but do not set every borrowing rate directly. The Federal Reserve: role of the FOMC describes the committee and its responsibilities.
The regular calendar contains eight scheduled meetings a year, with additional meetings possible when needed. Use the Federal Reserve: statements, minutes and projection materials for dates and documents rather than assuming every event occurs at a permanently fixed local time.
For a global trading audience, the important distinction is between a policy decision and the market's expectations of that decision. Prices may react to the difference, to new guidance about subsequent meetings, or to changes in the interpretation of the economic outlook.
Read each publication for its own purpose.
| Publication | What to look for | Common mistake |
|---|---|---|
| Decision and statement | Target range, policy wording, balance-sheet information and votes. | Reading only the rate headline. |
| Summary of Economic Projections, when issued | Participants’ projections for the economy and policy under their assumptions. | Treating the median dot as a binding committee promise. |
| Press conference | Explanation, qualifications and responses to questions. | Assuming the initial price move reflects all later information. |
| Minutes, generally three weeks later | A fuller account of the meeting discussion. | Treating minutes as a new rate decision. |
The official calendar identifies meetings associated with projection materials. Read the dates on the documents: an old projection table can remain searchable long after newer material is available.
A calendar may split the decision and press conference into separate events. Allow for that sequence when assessing exposure. A quiet initial reaction does not mean the remaining event window carries no uncertainty.
Calculate a rate change correctly.
One basis point is 0.01 percentage point. A 25-basis-point cut therefore lowers a rate by 0.25 percentage point. It does not mean a 25% reduction.
For a hypothetical example, a target range moving from 4.25–4.50% to 4.00–4.25% is a 25-basis-point cut at both ends. These ranges are invented teaching inputs, not a statement of the current policy rate.
Keep levels and changes in separate columns in a release journal. A market expecting the same 25-basis-point move may respond more to the accompanying outlook than to the arithmetic of the announced change.
An unchanged decision can still surprise.
Suppose the target range is left unchanged, as a consensus expected. One hypothetical statement emphasises persistent inflation and a need for more evidence. Another emphasises weakening employment and greater confidence about inflation. The identical rate decision can accompany materially different messages.
That does not give us a mechanical price forecast. Market participants may already have anticipated the wording; projections may send a different signal; the press conference may add qualifications. Record what was new relative to a timestamped prior expectation, rather than declaring every rise or fall to be proof of a simple “hawkish” or “dovish” label.
The labels generally refer to a relatively tighter or easier policy inclination. They are comparative descriptions. Always state the comparison: relative to the previous statement, the prior projections, or the market's expectations.
What the dot plot can and cannot tell you.
The dots show individual participants' assessments of appropriate policy associated with their economic outlooks. They are not a scheduled series of trades, a promise of future rate changes, or a probability distribution supplied by the committee.
A median can move when the distribution changes, but it does not capture every participant's view. Compare the spread of projections, their horizon and the accompanying economic assumptions. A change between projection rounds may reflect changed conditions rather than a broken promise.
The Federal Reserve: the longer-run inflation objective and PCE distinguishes the PCE-based inflation objective from CPI. Use the CPI guide and employment guide to understand important data without reducing the policy decision to one release.
Plan around the whole event window.
Use the economic calendar to find the scheduled events and verify them against the Fed's own calendar. Keep the time zone explicit. A UK viewing time can shift when US and UK daylight-saving transitions occur on different dates.
- Save the previous statement and any relevant projections.
- Write down the expectation source and its timestamp.
- Separate the initial decision from later communication.
- Observe changes in available quotes, spreads and fills.
- Review the complete documents after the event, including mixed messages.
A stop distance calculated before an announcement does not guarantee the eventual loss during a gap or fast repricing. A decision to observe without trading is compatible with learning how the event works.
Common FOMC questions.
Are FOMC minutes another interest-rate decision?
No. They describe the earlier meeting in greater detail and are published later. Their information may still affect expectations, but they are a different event.
Does a rate cut always make gold rise?
No. Expectations, the policy outlook, currency moves and other influences can matter. An expected cut and a surprise cut are different pieces of information.
Is the dot plot a forecast guarantee?
No. It contains participants’ conditional assessments. Future data and conditions can change those views.
Sources & assumptions.
Prepared by InsomniCapital; see our editorial approach. Sources checked on 2 October 2026. Schematics and hypothetical calculations are labelled educational illustrations. Historical observations identify their source, dates and method separately. Neither is a live quote, trade recommendation or reported trading result.
- Federal Reserve: role of the FOMC.
- Federal Reserve: statements, minutes and projection materials.
- Federal Reserve: the longer-run inflation objective and PCE.
Educational information only, not personalised investment advice. Leveraged trading carries a high risk of loss. Read our risk disclosure. InsomniCapital has an Axi affiliate relationship and may receive compensation for qualifying referrals. References are not endorsements of this guide.